Market Overview and Significance of the Cellular Concrete Market
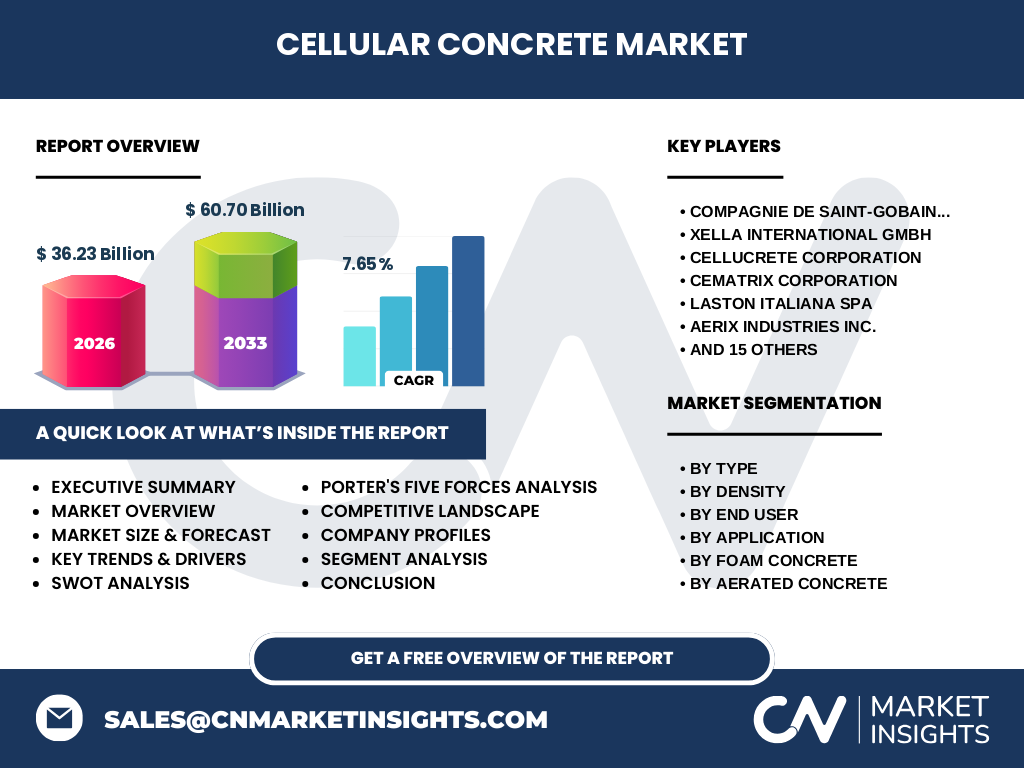
The Cellular Concrete Market represents a critical segment within global construction, defined by the inclusion of stable air cells in a cementitious matrix. With a 2026 valuation of $36.23 Billion, this sector is vital for sustainable development. It provides superior thermal efficiency and significant dead-load reduction, enabling complex architectural designs that traditional high-density concrete cannot support, fundamentally shifting material science expectations for modern infrastructure.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by urbanization and the demand for energy-efficient materials. Conversely, logistical hurdles such as specialized pumping equipment requirements and moisture sensitivity act as primary market restraints. Opportunities abound in the development of lightweight foam concrete for high-rise thermal insulation, though strict adherence to regional building codes, such as those governed by the International Building Code (IBC), remains a persistent challenge for manufacturers.
Emerging Trends Shaping Industry Trajectories
The industry is gravitating toward sustainable building envelopes and carbon-sequestering additives. We observe a significant shift in the Cellular Concrete Market toward autoclaved aerated concrete (AAC) due to its fire-resistant properties. Additionally, the move toward pre-fabricated modular construction is forcing players like H+H International A/S to innovate their curing processes to ensure higher compressive strength in lighter density ranges.
COVID-19 Impact and Recovery Analysis
The pandemic caused initial supply chain disruptions due to raw material procurement delays, particularly in cement and chemical foaming agents. However, the Cellular Concrete Market experienced a robust V-shaped recovery by 2023. This was driven by a surge in demand for infrastructure resilience and government-backed stimulus packages that prioritized modern, durable, and thermal-efficient construction materials, effectively insulating the sector from prolonged stagnation.
Competitive Benchmarking and Market Dynamics
The landscape is highly concentrated, with dominant entities like Compagnie de Saint-Gobain S.A. and Xella International GmbH leveraging R&D to set global benchmarks. Strategic dynamics focus on vertical integration, where companies control both the foaming agent supply chain and the final product delivery. Competitors often target specific regional niches, such as Cematrix Corporation focusing on specialized void filling for complex geological environments.
Executive Summary of Findings
Our analysis confirms the Cellular Concrete Market is on an aggressive growth trajectory, poised to reach $60.70 Billion by 2033. The CAGR of 7.65% reflects the structural transition from legacy heavy materials to lightweight, energy-efficient alternatives. Key stakeholders should prioritize technical differentiation in high-density applications and invest in localized manufacturing hubs near major port infrastructure to mitigate volatile logistics costs.
Market Forecast from 2027 to 2033
We project the market will expand from $36.23 Billion in 2026 to a substantial $60.70 Billion by 2033, growing at a CAGR of 7.65%. This growth is sustained by increasing public-sector spending on infrastructure and the urgent need for thermal insulation materials to meet stringent global energy efficiency standards, effectively making lightweight concrete a primary commodity in modern building projects.
Segmentation Analysis: Types and End-Users
The market is segmented by Type (Aerated vs. Foam), Density (High, Medium, Low), and End-User. Aerated concrete, specifically AAC, remains dominant in residential construction, while high-strength foam concrete is increasingly deployed for bridge abutment and road sub-bases. Understanding these segments is crucial; each serves distinct mechanical requirements—from structural load-bearing to lightweight void filling—that dictate the competitive intensity within specific, high-growth application fields.
Regional Market Performance and Geographic Distribution
Regional performance is heavily influenced by regulatory frameworks. The Asia-Pacific region leads due to rapid urbanization, while Europe remains a leader in sustainable building innovations. North America follows, with significant growth in infrastructure renewal projects. Localized constraints, such as specific soil conditions in different territories, require companies like Aerix Industries Inc. to tailor their formulation chemistries to ensure optimal performance against region-specific climatic challenges.
In-Depth Regional Market Review
In Europe, the drive toward carbon-neutral construction is pushing manufacturers toward non-autoclaved alternatives. Conversely, in the Middle East, extreme temperatures necessitate the usage of high-density foam concrete for roof insulation. Our research indicates that companies with strong local supply chains, such as ACICO Group in the Gulf region, are better positioned to capture market share compared to international players lacking proximity to regional port facilities.
Strategic Positioning of Leading Companies
Leading players employ distinct strategies: Cementir Holding S.p.A. focuses on sustainable binder technologies, whereas Cellucrete Corporation optimizes for rapid on-site application. LafargeHolcim SA utilizes its massive logistical network to dominate infrastructure supply, while firms like Litebuilt Structures LLC carve out market share through specialized modular components. This diverse strategic positioning creates a competitive equilibrium where R&D depth and logistical efficiency remain the primary differentiators.
Porter’s Five Forces Analysis
The Cellular Concrete Market exhibits moderate to high competitive rivalry. The threat of new entrants is mitigated by the capital intensity required for specialized foaming equipment. Supplier power is concentrated among global cement giants, while buyer power is rising as contractors demand high-performance, LEED-compliant materials. Substitution threats remain low as cellular concrete offers unique, non-negotiable thermal-to-weight ratios for specific engineering projects.
SWOT Analysis: Strategic Outlook
The strengths lie in superior thermal performance and lightweight characteristics. Weaknesses include technical sensitivity in batching and moisture curing. Opportunities are vast in green building certifications, while threats include volatile raw material costs and fluctuating regulatory standards. Strategic agility—the ability to pivot between residential demand and infrastructure projects—is the defining strength for industry leaders navigating these multifaceted market risks.
Value Chain and Industry Structure
The value chain begins with raw material providers (cement, fly ash, foaming agents) and flows through specialized chemical manufacturers to concrete producers. The chain culminates at the end-user site, where application-specific technology—like on-site foam generation—adds the final value. This structure emphasizes that operational excellence in batching and delivery is as significant as the quality of the raw cementitious binder itself.
Investment Insights and High-Potential Areas
Investors should focus on firms developing bio-based foaming agents and high-strength foam concrete for infrastructure-as-a-service. The $60.70 Billion forecast underscores the necessity of scaling regional manufacturing. High-potential areas include the integration of digital, automated dosing systems, which reduce batching errors and improve material consistency—a key bottleneck currently limiting the adoption of lightweight cellular concrete in hyper-sensitive high-rise construction projects.
Conclusion and Key Takeaways
The Cellular Concrete Market is transitioning from a niche construction material to a critical standard in global infrastructure. With a CAGR of 7.65%, the sector's growth is supported by sustainability mandates and technical innovation. Success will depend on the ability of manufacturers to harmonize high-performance outputs with local regulatory compliance and to optimize their value chains for resilience against fluctuating global raw material costs.
Research Methodology and Data Triangulation
Our baseline estimates are built by triangulating trade registry data, primary stakeholder interviews with global project leads, and secondary macroeconomic indicators. We cross-reference historical output data from key participants like CEMEX S.A.B. de C.V. with regional construction permits. This methodology ensures our 7.65% CAGR forecast accounts for both regional demand surges and technical capacity limitations within the industry’s current, highly specialized supply chain.
Scope of the Report and Limitations
This report covers the Cellular Concrete Market globally, analyzing segments from residential building materials to infrastructure void filling. The parameters exclude non-cementitious lightweight aggregates. Data is limited to publicly available financial disclosures and industry-validated proxies. While our 2033 projections reflect current trends, regional political stability and abrupt shifts in international trade policies regarding cement imports remain external variables that could influence long-term adoption rates.
Recent Developments and Market Announcements
Recent strategic moves, including partnerships between cement producers and tech innovators, signal a push toward digitized production. Announcements from AKG Gazbeton GmbH & Co. KG highlight investment in energy-efficient production facilities, while new product launches in the self-leveling foam concrete segment are expanding the material's footprint in industrial flooring. These developments align with the broader industry goal of achieving higher performance through technological precision.